A passive path for real estate ownership
Horizon 1031 brings its deep roots in the securitized real estate industry to every client relationship, pairing experience with true white glove care from first call to closing. We open a path to owning real estate passively in a tax-advantaged way, with a specialty in Delaware Statutory Trusts for 1031 exchange.
Fully passive. Exchange-eligible. Institutional quality.
A Delaware Statutory Trust is a legal entity, formed under Delaware law, that holds title to real estate on behalf of a group of investors. Rather than buying a whole property, an investor purchases a beneficial interest in the trust — a fractional, undivided share of a much larger asset than they could acquire, manage, or finance on their own.
That share entitles the investor to a pro-rata portion of the property's cash flow and, ultimately, its appreciation when the sponsor sells. Because the IRS treats a beneficial interest as real property for exchange purposes, a DST qualifies as replacement property under Section 1031 — while offering the same depreciation benefits as owning the building outright.
The difference is who does the work. The trust holds title, the sponsor manages the asset, and the investor receives a statement and a distribution — a truly passive form of real estate ownership.
Three identification rules. Two deadlines. One strategy to seamlessly satisfy your 1031 requirements.
From the day you close on the relinquished property, the clock is fixed by statute — not by how quickly a deal can be found. Miss the deadline to identify or to close and the exchange breaks, with the deferred tax coming due in full.
The exchange clock
A DST's due diligence is complete before it ever reaches an investor, which is what makes it possible to identify and close well inside these windows — sometimes simultaneously.
How many properties can be identified
The day-45 identification is made in writing to the qualified intermediary under one of three rules. A DST can be named under any of them, as the primary choice or as a backup.
Reduced exchange risk
The property is already acquired and vetted, so an investor buys a fractional interest rather than betting an entire exchange on one deal reaching the closing table.
Flexible investment amounts
DSTs accept any amount above the stated minimum, letting an exchanger deploy every dollar of proceeds — no cash left idle, no funds needed to close the gap.
Backup identification
A DST can be named alongside a primary replacement property, ready to absorb the exchange if that deal falls through before day 45.
Debt replacement
Most DSTs carry moderate, non-recourse leverage — roughly 20–55% LTV — so an exchanger can replace mortgage debt without personally qualifying for a new loan.
Split one exchange across several properties, asset classes, and markets
Low minimums make it practical to spread proceeds across multiple DSTs — a straightforward way to manage the concentration risk that comes with owning a single building.
Asset class and lease type
Investors seeking stable income often favor net-lease assets with long-term, credit-tenant leases that push taxes, insurance, and maintenance onto the tenant. Others lean toward shorter-lease property — multifamily, self-storage, hospitality — where rents can adjust to market faster. Many split proceeds across both, since real estate is cyclical and asset classes move through a cycle differently.
Geography
A common strategy is using a DST to reposition capital away from a market facing political risk, rising insurance costs, or softening demographics, and toward one with stronger job and population growth — without needing to find or vet a property manager in an unfamiliar city yourself.
A passive structure, backed by five layers of vetting before it reaches you
Giving up day-to-day control is the trade for a level of underwriting most individual buyers never get. Every offering we bring to a client has already passed through each of these five layers.
Sponsor underwriting
Sponsors typically underwrite hundreds to thousands of potential deals a year and bring only a small fraction to market.
Legal counsel review
Independent counsel drafts the offering's Private Placement Memorandum, disclosing everything material about the sponsor, the property, and the deal terms.
Third-party research
Independent research firms analyze each offering in depth, producing commentary that informs the final layer of review before it reaches a client.
Broker-dealer review
Our broker-dealer partners conduct the final, deciding review of every offering, approving or declining it against consistent underwriting standards.
Lender underwriting
For levered offerings, the lender adds its own review — confirming value through appraisal, assessing environmental risk, and underwriting to loan-to-value and debt-service coverage.
What you're giving up, in exchange for what you gain
A DST's passive nature is its main appeal — and the source of its three real trade-offs. We walk through each with every client before any property is identified.
Loss of control
You hold a beneficial interest in the trust, but the sponsor retains control of asset and property management, including the ultimate decision to sell.
Illiquidity
There is no secondary market. A DST can occasionally be sold to a third party mid-hold, but investors should plan on a full 2–10 year commitment.
Fee structure
Acquisition, sponsor, and placement fees are built into a single purchase price rather than billed separately — though DSTs are commonly acquired below appraised value, which can help offset that load.
A DST offers a simplified exchange into extensively vetted, institutional-grade property — a passive investment carrying the potential for cash flow, appreciation, and the same tax advantages as owning real estate directly.
Notes on exchanges, structuring, and the DST market
1031 Exchange Rules: Deadlines, Identification, and DSTs
A 1031 exchange can defer gain when you sell real estate held for investment or business use and acquire qualifying replacement property. Meeting the deadlines is essential, but choosing suitable…
DST Diversification: Strategic Portfolio Allocation
Property Diversification The DST marketplace is extensive and diverse, and with DST investment minimums typically set at $100,000, DST investors can practically diversify their real estate holdings…
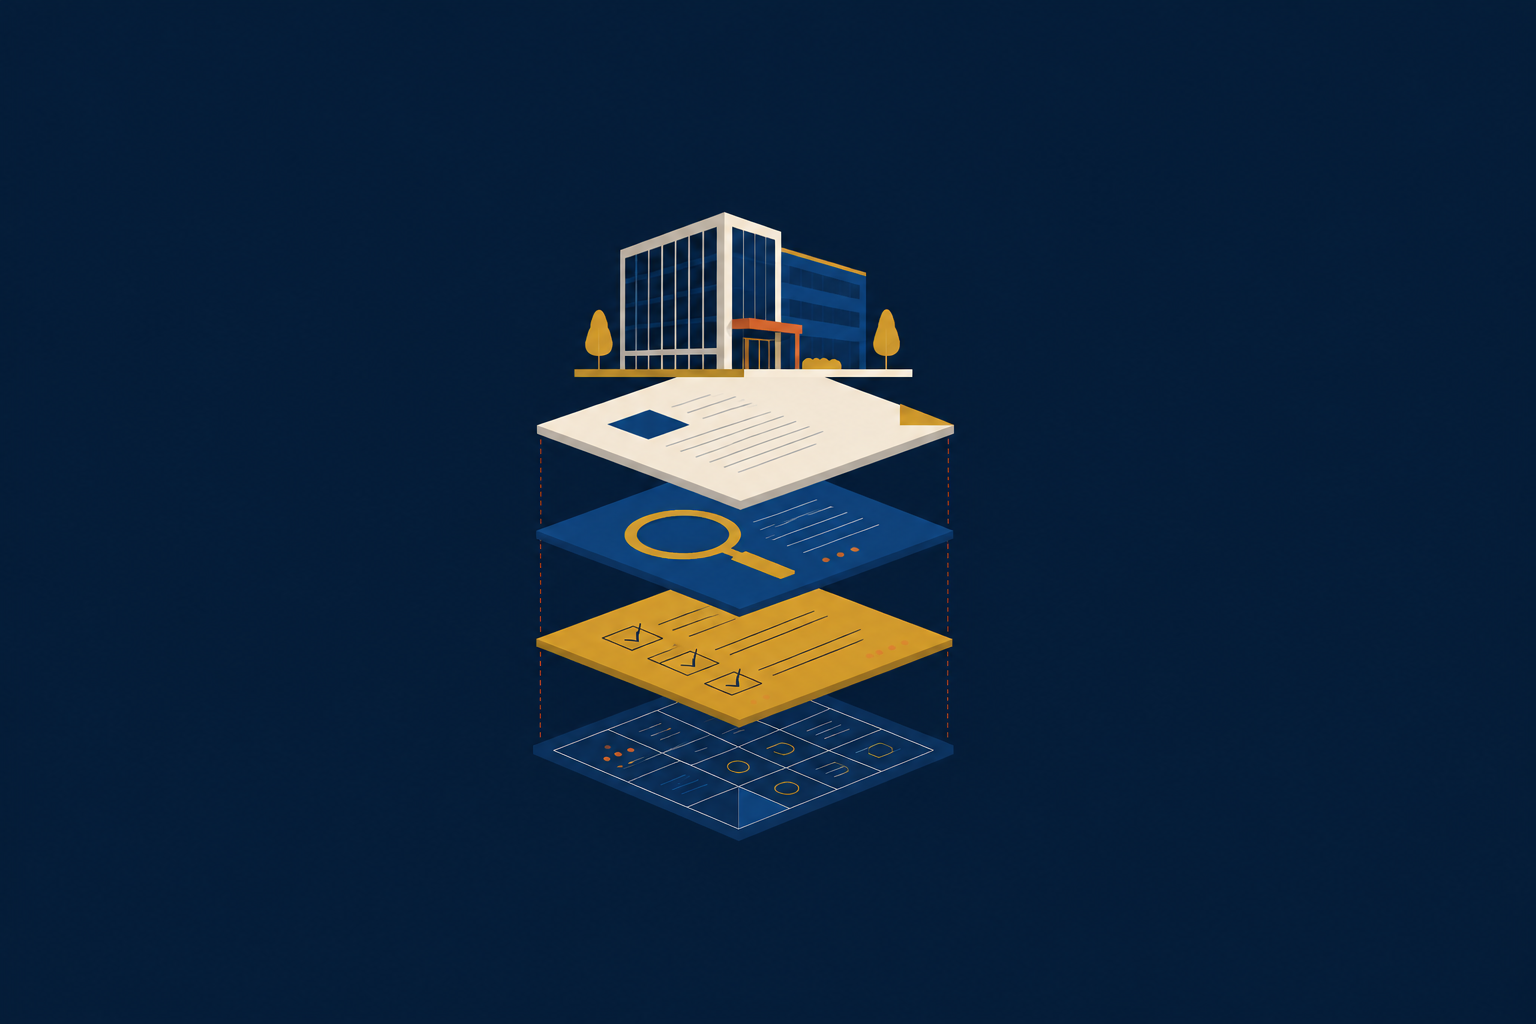
DST Due Diligence: A Look at Each Layer
A key characteristics of DSTs, and a mitigating factor for the inherent loss of control associated with a DST investment, is the significant due diligence an offering passes through before becoming…